Saudi AML Compliance in 2026: Why Continuous Risk Monitoring Is Becoming a Business Necessity
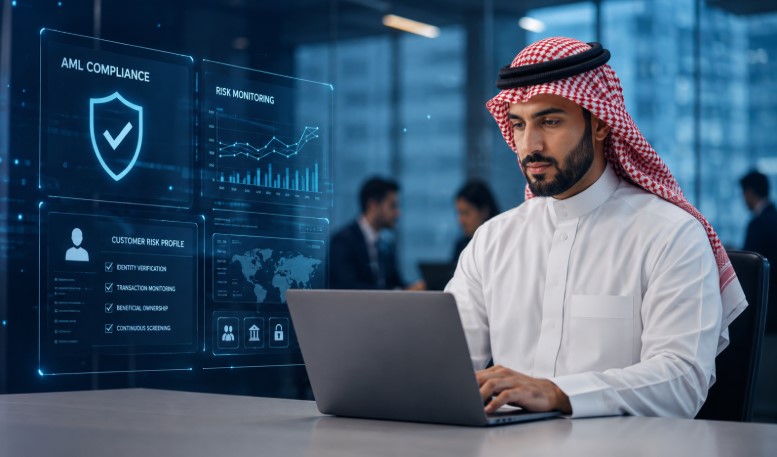
Saudi Arabia’s financial sector is rapidly evolving through digital banking, fintech, payment services, and investment activities under Vision 2030. As financial services become increasingly connected, financial crime risks can also evolve quickly. As a result, AML compliance in Saudi Arabia is moving beyond one-time customer checks toward continuous monitoring and proactive financial crime prevention. SAMA requires financial institutions to continuously monitor transactions, documents, and customer data to ensure that activity remains consistent with their knowledge of the customer, business activities, and risk profile. Source: Saudi Central Bank (SAMA), Section 7 – Monitoring of Transactions and Activities. SAMA Rulebook
Why Continuous Risk Monitoring Matters
Customer risk can change throughout a business relationship. Changes in transaction behavior, business activities, geographic exposure, or other risk factors may increase a customer’s ML/TF risk after onboarding. SAMA therefore requires institutions to apply a risk-based monitoring approach, with enhanced monitoring for higher-risk customers and transactions. Source: SAMA, Section 7 – Monitoring of Transactions and Activities. [Source]
Key Areas of Continuous AML Monitoring
Dynamic Customer Risk Assessment
Financial institutions should continuously update customer risk profiles using relevant customer, transaction, business, and beneficial ownership information. SAMA requires institutions to apply ongoing due diligence, keep customer information updated, reassess customer risks based on transactions and activities, and apply more frequent reviews to higher-risk customers.
Source: SAMA, Due Diligence Measures, Paragraphs 3.7–3.8. SAMA Rulebook
Real-Time Transaction Monitoring
Transaction monitoring is a core element of effective AML compliance. SAMA states that financial institutions must monitor transactions and activities on an ongoing basis and use appropriate technological systems to identify unusual or unexpected customer behavior. The framework also emphasizes the ability to analyze and detect unusual transactions and patterns in real time. Source: SAMA, Section 7 – Monitoring of Transactions and Activities, Paragraphs 7.4–7.7. SAMA Rulebook
Beneficial Ownership and Continuous Screening
Understanding beneficial ownership is an important part of customer due diligence. SAMA requires financial institutions to identify and verify beneficial owners and continuously apply due diligence based on the level of risk. Institutions must also verify customers and beneficial owners against relevant sanctions lists as part of their AML controls.
Source: SAMA, Due Diligence Measures, Paragraphs 3.1, 3.7 and 3.12. [Source]
The Role of Technology
Technology plays an increasingly important role in effective AML monitoring. SAMA states that manual transaction monitoring alone is not sufficient and requires appropriate electronic systems for continuous oversight. At the same time, institutions must maintain qualified employees and should not rely solely on technology when conducting AML monitoring and investigations. Source: SAMA, Section 7, Paragraphs 7.5 and 7.8. SAMA Rulebook
In 2026, continuous risk monitoring is becoming an essential component of effective Saudi AML compliance. Moving from periodic reviews toward dynamic risk assessment, continuous transaction monitoring, updated customer information, and technology-enabled controls can help organizations identify emerging risks earlier and strengthen their AML frameworks. Source: SAMA, Anti-Money Laundering Law, Article 13, and SAMA AML/CTF Monitoring Guidance. SAMA Monitoring Guidance | [Source]
FACEKI AML Service, based in Riyadh, Saudi Arabia, provides identity verification, AML screening, sanctions screening, transaction monitoring, and risk-management solutions designed to help organizations strengthen their financial crime compliance frameworks and support alignment with applicable SAMA, CMA, and IA requirements in KSA.
